


Overview
A quieter market, with different directions beneath the headline
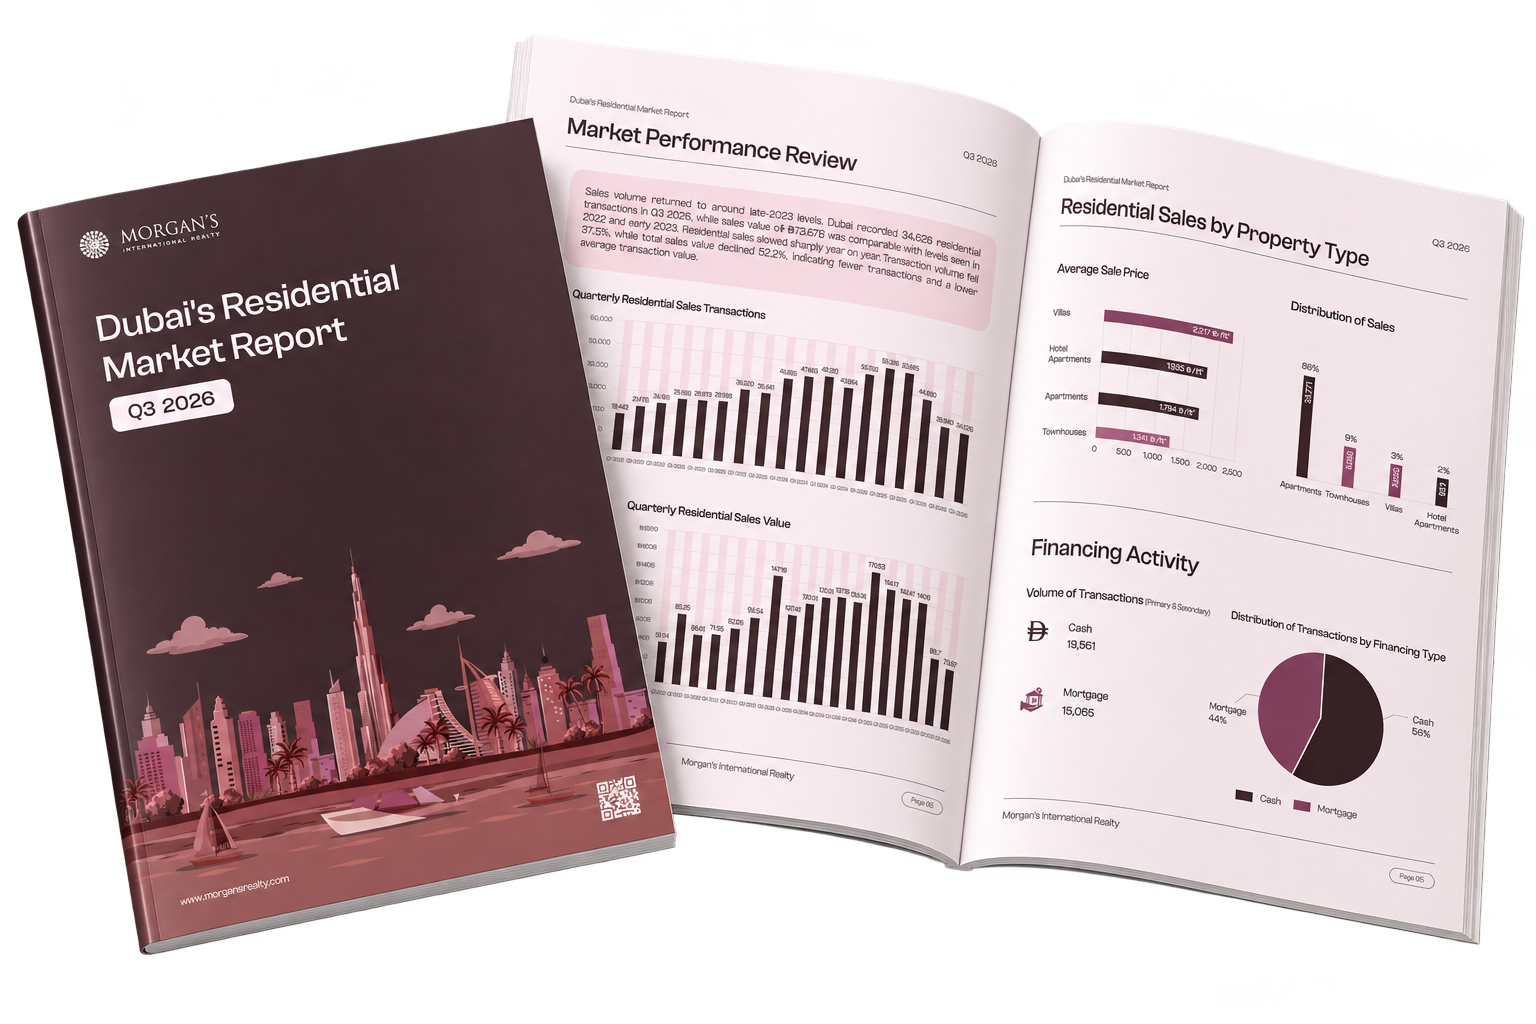
Dubai recorded 34,626 residential sales worth AED 73.67 billion in Q3 2026. Transaction volume declined 4% quarter-on-quarter, while sales value fell 17%. The average transaction value decreased 14% to AED 2.13 million. The annual comparison shows a sharper adjustment. Transaction volume was 37.5% below Q3 2025, while sales value declined 52.2%. Quarterly sales volumes returned to approximately late-2023 levels, with total transaction value comparable to levels recorded during 2022 and early 2023. These headline figures conceal an important divergence. Completed homes attracted more transactions than in Q2, while off-plan sales continued to moderate. Understanding that distinction matters more than treating Dubai’s residential market as a single trend.
Market Composition
Completed homes strengthen as off-plan sales moderate
Ready-home transactions increased 11% quarter-on-quarter to 9,765, accounting for 28% of residential sales. Their combined value reached AED 26.86 billion, down 7% from Q2. Average transacted prices in the ready segment rose 18% quarterly to AED 1,914 per square foot. This reflects the properties sold during the quarter and should not be interpreted as an equivalent increase in the value of comparable homes. Despite the quarterly improvement in activity, ready-home transaction volumes remained approximately 44% below Q3 2025. Off-plan properties retained the majority of activity, representing 72% of residential transactions. The segment recorded 24,861 sales worth AED 46.81 billion, with volumes declining 9% and sales value falling 22% quarter-on-quarter. Average off-plan prices fell 9% quarterly to AED 1,750 per square foot, approximately 14% below Q4 2025. Initial sales accounted for 91% of off-plan transactions, with resales representing the remaining 9%. The divergence may indicate stronger support from end-users seeking completed homes. Transaction records alone, however, do not establish buyer motivation.
Leasing Market
More rental registrations, lower median rent per square foot
Residential rental registrations increased 34% quarter-on-quarter to 155,804. Renewals accounted for 83,916 registrations, or 54% of activity, while new contracts represented 71,888 registrations, or 46%. At the same time, median annual rent per square foot declined 6% to AED 87. The combined annual value represented by registered contracts reached AED 14.45 billion, up 42% from Q2. These movements highlight the distinction between leasing activity and rental pricing. More registered contracts do not necessarily mean rising rents or an equivalent increase in households entering the market, particularly when renewals account for more than half of registrations. For landlords, pricing decisions require current evidence from comparable properties, alongside an understanding of competing availability and renewal conditions.
Supply Pipeline
Scheduled deliveries remain concentrated in 2027 and 2028
As of September 2026, the recorded residential pipeline comprised 479,105 units across 1,713 projects. Of these, 290,529 units—approximately 61%—were scheduled for delivery during 2027 and 2028. Apartments accounted for 86% of the pipeline, followed by townhouses and villas at 13% and hotel apartments at 1%. Among the communities covered in the report, Dubai South had 41,932 scheduled units, followed by Jumeirah Village Circle with 32,864, Dubai Residence Complex with 23,548 and Business Bay with 20,431. Scheduled supply represents planned delivery, with completion dates subject to construction progress and revised handover schedules. The market impact will depend on when homes become available, where deliveries concentrate and how effectively each community absorbs additional inventory.
Outlook
Pricing discipline becomes more important as buyers compare their options
Q3 2026 points to a market in which performance increasingly depends on completion status, location, property characteristics and price. Completed homes gained transaction activity, but the quarterly improvement sits within a substantially quieter annual market. Off-plan sales remained dominant while recording lower volumes and softer average pricing. High-value activity also moderated. Prime transactions declined 26% quarter-on-quarter to 680, super-prime transactions fell 23% to 94, and trophy sales decreased from 18 to 10. The small number of trophy transactions makes percentage changes particularly sensitive to individual deals. For sellers and developers, the next phase calls for closer attention to competing properties, achievable pricing and approaching supply. For buyers, the broader slowdown makes careful comparison more valuable, while reinforcing the need to assess each property on its own merits.